or call 1 888-378-9012

or call 1 888-378-9012

Get Quality Healthcare Without overspending

IBN360 helps self-employed professionals, 1099 workers, contractors, entrepreneurs, and families access affordable healthcare and other resources they need.

Get Quality Healthcare Without overspending

IBN360 helps self-employed professionals, 1099 workers, contractors, entrepreneurs, and families access affordable healthcare and other resources they need.

Explore Your Options

A Complete Solution for

Healthcare and More

IBN360 helps self-employed, 1099, and independent professionals get access to healthcare, financial, protection, and business

resources they may not receive through a traditional employer.

Healthcare

Navigation

Explore healthcare resources and learn about options that may be available.

Financial

Wellness

Find resources for managing money, debt, savings, and financial goals.

Protection

Planning

Learn about protection resources and available planning options.

Business

Resources

Find information and resources for freelancers, contractors, and entrepreneurs.

Professional

Guidance

Start with a few questions and explore from there.

Explore Your Options

A Complete Solution for

Healthcare and More

IBN360 helps self-employed, 1099, and independent professionals get access to healthcare, financial, protection, and business resources they may not receive through a traditional employer.

Healthcare

Navigation

Explore healthcare resources and learn about options that may be available.

Financial

Wellness

Find resources for managing money, debt, savings, and financial goals.

Protection

Planning

Learn about protection resources and available planning options.

Business

Resources

Find information and resources for freelancers, contractors, and entrepreneurs.

Professional

Guidance

Start with a few questions and explore from there.

Built for people who work differently

Traditional benefits don't always work for people outside traditional employment. IBN360 provides healthcare and other resources for:

  • Self-employed professionals who manage their own benefits.

  • 1099 workers and contractors who don't receive traditional employer benefits.

  • Freelancers and entrepreneurs who need resources that work outside a traditional workplace.

  • People between jobs who need another way to access healthcare.

  • Individuals and families looking for affordable healthcare options.

Built for people who work differently

Traditional benefits don't always work for people outside traditional employment.

IBN360 provides healthcare and other resources for:

  • Self-employed professionals who manage their own benefits.

  • 1099 workers and contractors who don't receive traditional employer benefits.

  • Freelancers and entrepreneurs who need resources that work outside a traditional workplace.

  • People between jobs who need another way to access healthcare.

  • Individuals and families looking for affordable healthcare options.

REAL-LIFE SITUATIONS

WHERE IBN360
FITS

Independent work comes with a lot to manage. Here are a few everyday situations and resources you can explore through IBN360.

01

Juggling Work, Bills & Healthcare

An independent professional may be managing clients, monthly expenses, and healthcare decisions at the same time.

Explore: Healthcare navigation and educational resources.
02

Managing an Income That Changes

Freelance and contract income can vary while bills and everyday financial responsibilities continue.

Explore: Budgeting, saving, debt, and financial wellness resources.
03

Thinking About What Comes Next

Planning for income, family responsibilities, and the future can be another thing to manage alongside work.

Explore: Protection planning information and educational resources.
04

Running a Business & Managing Life

Business owners often balance customers, daily operations, personal finances, and other responsibilities.

Explore: Business and independent professional resources.

Example situations are for educational and illustrative purposes only. Resources, eligibility, costs, benefits, and availability may vary.

Workshops

Support that isn't tied to one employer

The way people work has changed. Benefits should work for people who are self-employed, freelance, contract, run a business, or move between jobs.

  • Explore: See what's available based on what you're looking for.

  • Learn: Understand your options in simple language.

  • Ask: Get additional guidance when you have questions.

  • Decide: Choose what makes sense for your situation.

No pressure. No complicated process.

Member Testimonials

"Health Insurance Success Story"

Finally an affordable health insurance policy for the whole family. Independent contractors and 1099 workers are no longer out in the cold when it comes to healthcare. Be rewarded for your healthy lifestyle and tenacity to go it alone and don’t worry about premiums that drain your bank account.

"Licensed IBN360

Specialist"

I’m in awe of how simple and fast the process is to get clients price quotes and breakdown of the advantages IBN360 offers so that they can compare to their current situations. Not one has been disappointed with what they’ve heard. After a quick 10-minute information gathering, clients are set up and good to go. You can feel their sighs of relief.

"Health Insurance Success Story"

With health insurance premiums continuing to rise, I am so grateful to have found this program. Now I finally have an affordable and customizable health insurance plan for me and my family. Thank you IBN360!

"Health Insurance

Quote"

The switch to this plan saved my wife $450/mth ($5,400/yr); which also included a deductible that was $6,000 lower. Her PCP was in-network. Our family is thrilled and grateful to have such a positive financial impact.

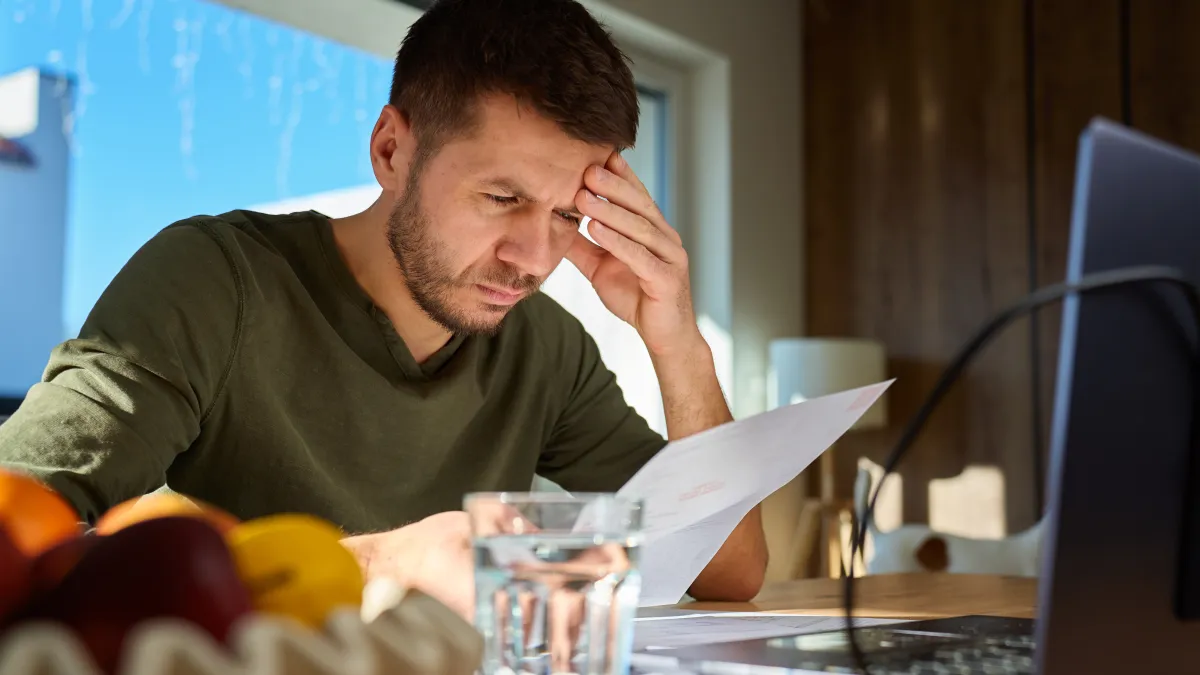
Man reviewing paperwork at home after leaving a job and trying to understand his health insurance options

Just Left Your Job? Here’s What Happens to Your Health Coverage Next | IBN360

March 20, 2026•4 min read

Leaving a job can mess with more than your paycheck. For a lot of people, it also means suddenly figuring out what happens to their health insurance, how fast they need to act, and whether they are about to get hit with a huge monthly bill. That can feel especially stressful when everything else already feels up in the air.

The good news is that losing job-based coverage usually gives you a path forward. If you left voluntarily, were laid off, or were let go, you may still have time to choose new coverage without waiting for the next open enrollment period. The key is knowing what your options are and how to avoid a gap that leaves you exposed right when you need care most.


Your first move is understanding when your job-based coverage ends

If you lose health insurance through work, you usually have a few possible next steps: you can enroll in a Marketplace plan, continue your employer coverage for a limited time through COBRA if it is available, or find out whether you qualify for Medicaid or CHIP. HealthCare.gov says that if you leave your job for any reason and lose job-based insurance, you qualify for a Special Enrollment Period. In most cases, you need to apply within 60 days of losing that coverage. For this Special Enrollment Period, you need to apply for Marketplace coverage within 60 days of losing your job-based coverage. Your coverage can start the first day of the month after you lose your job-based coverage, so applying before your employer plan ends can help reduce the chance of a coverage gap. (Source: HealthCare.gov)

Once you know that date, the next step is comparing your replacement options based on cost, timing, and how much continuity you need with your doctors and prescriptions.


COBRA can keep the same plan, but it can cost a lot more

COBRA is often the most familiar option because it lets you keep the same employer health plan for a limited time after your job ends. That can be helpful if you are in the middle of treatment, want to keep the same provider network, or just do not want to switch plans immediately. The catch is the price. The Department of Labor says COBRA usually requires you to pay the full premium yourself, plus up to a 2% administrative fee. In most cases, coverage can last 18 to 36 months, and you generally have 60 days to enroll after employer coverage ends. COBRA can also protect dependents, since spouses and children may qualify even if the former employee does not enroll. (Source: U.S. Department of Labor)

That is why COBRA is often less of a long-term answer and more of a bridge. If the monthly cost feels too steep, the next option to look at is the Marketplace.


Marketplace coverage may be more affordable than people expect

A lot of people assume Marketplace plans automatically mean higher risk or worse coverage, but that is not always true. Depending on your income, you may qualify for premium tax credits that lower what you pay each month, and some people may qualify for Medicaid or CHIP instead. CMS reported that for 2026, the average HealthCare.gov premium after tax credits is projected to be $50 per month for the lowest-cost plan for eligible enrollees. That does not mean every plan is cheap, and it does not apply to everyone, but it does show why it is worth checking your actual options before assuming COBRA is your only realistic choice. CMS also reported that in 2026, nearly 60% of eligible re-enrollees will have access to a plan in their chosen health plan category at or below $50 after tax credits. (Source: CMS)

Once you see the real numbers, the decision gets clearer. The best fit often comes down to whether you want to keep the exact same plan for a short time or lower your monthly cost and choose a new path.


The smartest choice is the one that works in real life

This is where people can get tripped up. A plan that looks fine on paper may still be a bad fit if your doctors are out of network, your deductible is too high to manage, or your prescriptions are handled differently than before. If you just left a job, this is not the moment to choose based only on the monthly premium. It is the moment to ask what you would actually be able to afford if you needed care next month, not just what looks cheapest today.

If you want to keep learning before making a decision, start with the IBN360 Blog Hub, then read How to Know If a Health Insurance Plan Is Good (Simple Checklist) and Health Insurance for 1099 Contractors: Choose a Plan That Fits Your Budget. And if you want help narrowing down what may fit your budget, doctors, and real-life needs, book a coverage review with IBN360 Healthcare.

Get covered with confidence through IBN360. Book a call today.
health insurance after leaving a jobwhat happens to health insurance when you leave a jobhealth coverage after job loss
Back to Blog

Member Testimonials

"Health Insurance Success Story"

Finally an affordable health insurance policy for the whole family. Independent contractors and 1099 workers are no longer out in the cold when it comes to healthcare. Be rewarded for your healthy lifestyle and tenacity to go it alone and don’t worry about premiums that drain your bank account.

"Licensed IBN360

Specialist"

I’m in awe of how simple and fast the process is to get clients price quotes and breakdown of the advantages IBN360 offers so that they can compare to their current situations. Not one has been disappointed with what they’ve heard. After a quick 10-minute information gathering, clients are set up and good to go. You can feel their sighs of relief.

"Health Insurance Success Story"

With health insurance premiums continuing to rise, I am so grateful to have found this program. Now I finally have an affordable and customizable health insurance plan for me and my family. Thank you IBN360!

"Health Insurance

Quote"

The switch to this plan saved my wife $450/mth ($5,400/yr); which also included a deductible that was $6,000 lower. Her PCP was in-network. Our family is thrilled and grateful to have such a positive financial impact.

Man reviewing paperwork at home after leaving a job and trying to understand his health insurance options

Just Left Your Job? Here’s What Happens to Your Health Coverage Next | IBN360

March 20, 2026•4 min read

Leaving a job can mess with more than your paycheck. For a lot of people, it also means suddenly figuring out what happens to their health insurance, how fast they need to act, and whether they are about to get hit with a huge monthly bill. That can feel especially stressful when everything else already feels up in the air.

The good news is that losing job-based coverage usually gives you a path forward. If you left voluntarily, were laid off, or were let go, you may still have time to choose new coverage without waiting for the next open enrollment period. The key is knowing what your options are and how to avoid a gap that leaves you exposed right when you need care most.


Your first move is understanding when your job-based coverage ends

If you lose health insurance through work, you usually have a few possible next steps: you can enroll in a Marketplace plan, continue your employer coverage for a limited time through COBRA if it is available, or find out whether you qualify for Medicaid or CHIP. HealthCare.gov says that if you leave your job for any reason and lose job-based insurance, you qualify for a Special Enrollment Period. In most cases, you need to apply within 60 days of losing that coverage. For this Special Enrollment Period, you need to apply for Marketplace coverage within 60 days of losing your job-based coverage. Your coverage can start the first day of the month after you lose your job-based coverage, so applying before your employer plan ends can help reduce the chance of a coverage gap. (Source: HealthCare.gov)

Once you know that date, the next step is comparing your replacement options based on cost, timing, and how much continuity you need with your doctors and prescriptions.


COBRA can keep the same plan, but it can cost a lot more

COBRA is often the most familiar option because it lets you keep the same employer health plan for a limited time after your job ends. That can be helpful if you are in the middle of treatment, want to keep the same provider network, or just do not want to switch plans immediately. The catch is the price. The Department of Labor says COBRA usually requires you to pay the full premium yourself, plus up to a 2% administrative fee. In most cases, coverage can last 18 to 36 months, and you generally have 60 days to enroll after employer coverage ends. COBRA can also protect dependents, since spouses and children may qualify even if the former employee does not enroll. (Source: U.S. Department of Labor)

That is why COBRA is often less of a long-term answer and more of a bridge. If the monthly cost feels too steep, the next option to look at is the Marketplace.


Marketplace coverage may be more affordable than people expect

A lot of people assume Marketplace plans automatically mean higher risk or worse coverage, but that is not always true. Depending on your income, you may qualify for premium tax credits that lower what you pay each month, and some people may qualify for Medicaid or CHIP instead. CMS reported that for 2026, the average HealthCare.gov premium after tax credits is projected to be $50 per month for the lowest-cost plan for eligible enrollees. That does not mean every plan is cheap, and it does not apply to everyone, but it does show why it is worth checking your actual options before assuming COBRA is your only realistic choice. CMS also reported that in 2026, nearly 60% of eligible re-enrollees will have access to a plan in their chosen health plan category at or below $50 after tax credits. (Source: CMS)

Once you see the real numbers, the decision gets clearer. The best fit often comes down to whether you want to keep the exact same plan for a short time or lower your monthly cost and choose a new path.


The smartest choice is the one that works in real life

This is where people can get tripped up. A plan that looks fine on paper may still be a bad fit if your doctors are out of network, your deductible is too high to manage, or your prescriptions are handled differently than before. If you just left a job, this is not the moment to choose based only on the monthly premium. It is the moment to ask what you would actually be able to afford if you needed care next month, not just what looks cheapest today.

If you want to keep learning before making a decision, start with the IBN360 Blog Hub, then read How to Know If a Health Insurance Plan Is Good (Simple Checklist) and Health Insurance for 1099 Contractors: Choose a Plan That Fits Your Budget. And if you want help narrowing down what may fit your budget, doctors, and real-life needs, book a coverage review with IBN360 Healthcare.

Get covered with confidence through IBN360. Book a call today.
health insurance after leaving a jobwhat happens to health insurance when you leave a jobhealth coverage after job loss
Back to Blog

Workshops

YOUR GOALS. YOUR CHOICES.

Get the Healthcare You Need at a Price That Works for You

Meet with an IBN360 specialist to learn about our healthcare network, review affordable pricing options, and get a quote based on your needs.

Workshops

YOUR GOALS. YOUR CHOICES.

Get the Healthcare You Need at a Price That Works for You

Meet with an IBN360 specialist to learn about our healthcare network, review affordable pricing options, and get a quote based on your needs.

Copyright (c) 2026 IBN360. All rights reserved

Privacy Policy I Terms and Conditions

Certain Programs and Benefits May Vary by States

IBN360 is a health coverage navigation platform. IBN360 is not a insurance carrier. All coverage discussions, quotes, and enrollments are handled by licensed specialists. Coverage availability, rates, and benefits vary by state.