or call 1 888-378-9012

or call 1 888-378-9012

Get Quality Healthcare Without overspending

IBN360 helps self-employed professionals, 1099 workers, contractors, entrepreneurs, and families access affordable healthcare and other resources they need.

Get Quality Healthcare Without overspending

IBN360 helps self-employed professionals, 1099 workers, contractors, entrepreneurs, and families access affordable healthcare and other resources they need.

Explore Your Options

A Complete Solution for

Healthcare and More

IBN360 helps self-employed, 1099, and independent professionals get access to healthcare, financial, protection, and business

resources they may not receive through a traditional employer.

Healthcare

Navigation

Explore healthcare resources and learn about options that may be available.

Financial

Wellness

Find resources for managing money, debt, savings, and financial goals.

Protection

Planning

Learn about protection resources and available planning options.

Business

Resources

Find information and resources for freelancers, contractors, and entrepreneurs.

Professional

Guidance

Start with a few questions and explore from there.

Explore Your Options

A Complete Solution for

Healthcare and More

IBN360 helps self-employed, 1099, and independent professionals get access to healthcare, financial, protection, and business resources they may not receive through a traditional employer.

Healthcare

Navigation

Explore healthcare resources and learn about options that may be available.

Financial

Wellness

Find resources for managing money, debt, savings, and financial goals.

Protection

Planning

Learn about protection resources and available planning options.

Business

Resources

Find information and resources for freelancers, contractors, and entrepreneurs.

Professional

Guidance

Start with a few questions and explore from there.

Built for people who work differently

Traditional benefits don't always work for people outside traditional employment. IBN360 provides healthcare and other resources for:

  • Self-employed professionals who manage their own benefits.

  • 1099 workers and contractors who don't receive traditional employer benefits.

  • Freelancers and entrepreneurs who need resources that work outside a traditional workplace.

  • People between jobs who need another way to access healthcare.

  • Individuals and families looking for affordable healthcare options.

Built for people who work differently

Traditional benefits don't always work for people outside traditional employment.

IBN360 provides healthcare and other resources for:

  • Self-employed professionals who manage their own benefits.

  • 1099 workers and contractors who don't receive traditional employer benefits.

  • Freelancers and entrepreneurs who need resources that work outside a traditional workplace.

  • People between jobs who need another way to access healthcare.

  • Individuals and families looking for affordable healthcare options.

REAL-LIFE SITUATIONS

WHERE IBN360
FITS

Independent work comes with a lot to manage. Here are a few everyday situations and resources you can explore through IBN360.

01

Juggling Work, Bills & Healthcare

An independent professional may be managing clients, monthly expenses, and healthcare decisions at the same time.

Explore: Healthcare navigation and educational resources.
02

Managing an Income That Changes

Freelance and contract income can vary while bills and everyday financial responsibilities continue.

Explore: Budgeting, saving, debt, and financial wellness resources.
03

Thinking About What Comes Next

Planning for income, family responsibilities, and the future can be another thing to manage alongside work.

Explore: Protection planning information and educational resources.
04

Running a Business & Managing Life

Business owners often balance customers, daily operations, personal finances, and other responsibilities.

Explore: Business and independent professional resources.

Example situations are for educational and illustrative purposes only. Resources, eligibility, costs, benefits, and availability may vary.

Workshops

Support that isn't tied to one employer

The way people work has changed. Benefits should work for people who are self-employed, freelance, contract, run a business, or move between jobs.

  • Explore: See what's available based on what you're looking for.

  • Learn: Understand your options in simple language.

  • Ask: Get additional guidance when you have questions.

  • Decide: Choose what makes sense for your situation.

No pressure. No complicated process.

Member Testimonials

"Health Insurance Success Story"

Finally an affordable health insurance policy for the whole family. Independent contractors and 1099 workers are no longer out in the cold when it comes to healthcare. Be rewarded for your healthy lifestyle and tenacity to go it alone and don’t worry about premiums that drain your bank account.

"Licensed IBN360

Specialist"

I’m in awe of how simple and fast the process is to get clients price quotes and breakdown of the advantages IBN360 offers so that they can compare to their current situations. Not one has been disappointed with what they’ve heard. After a quick 10-minute information gathering, clients are set up and good to go. You can feel their sighs of relief.

"Health Insurance Success Story"

With health insurance premiums continuing to rise, I am so grateful to have found this program. Now I finally have an affordable and customizable health insurance plan for me and my family. Thank you IBN360!

"Health Insurance

Quote"

The switch to this plan saved my wife $450/mth ($5,400/yr); which also included a deductible that was $6,000 lower. Her PCP was in-network. Our family is thrilled and grateful to have such a positive financial impact.

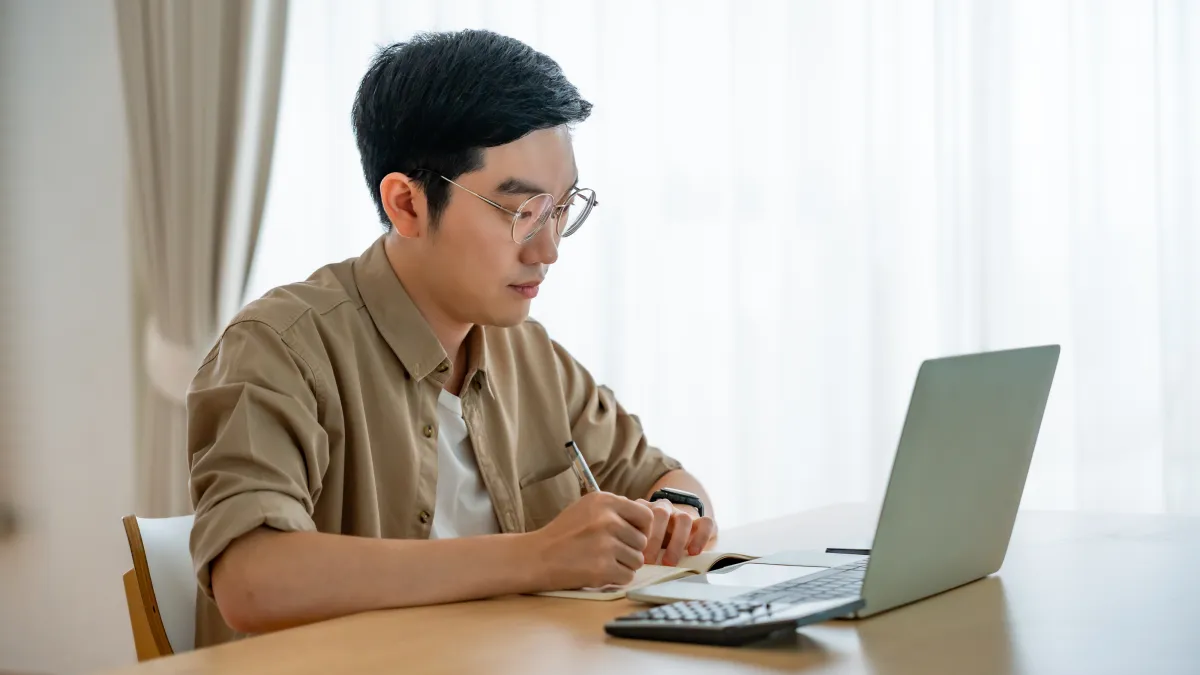
Freelancer working on a laptop in a home office, comparing health insurance options and out-of-pocket costs.

Health Insurance for Freelancers: Why You Can Be “Covered” and Still Owe Thousands | IBN360

February 14, 2026•4 min read

You buy a plan, you pay the premium, and you breathe a little easier because you did the responsible thing. Then the first real medical moment shows up, a lab, a scan, a specialist visit, a new prescription, and the bill lands with a number that makes you check your email twice.

This is the freelancer whiplash: you are insured, but your bank account still feels uninsured. When you are a 1099 worker, you do not have HR translating the fine print, so it is easy to choose coverage that looks affordable until you actually use it.


The high deductible trap that turns “covered” into “still paying”

Most self-employed people shop by monthly premium first because that is the only number that feels stable. The problem is that many Marketplace plans push more of the cost to you up front through deductibles and coinsurance. In 2026, KFF’s analysis of Healthcare.gov plan listings finds that the average deductible across Bronze Marketplace plans is $7,476 (a simple average across available plans), and catastrophic plans generally set the deductible equal to the ACA out-of-pocket maximum, which in 2026 is $10,600 for an individual. (Source: KFF)

Here is how this usually plays out: you go to care early in the year, you have not hit the deductible, and you pay most of the bill. Even after you meet the deductible, coinsurance can keep you paying a percentage on many services until you hit the out-of-pocket maximum. That is why someone can genuinely be insured and still owe thousands, especially if they need imaging, outpatient procedures, or ongoing specialist care.


Networks matter more than people think, especially when you need care fast

Freelancers do not always have the luxury of planning care perfectly. When something hurts, you go where you can get an appointment. That is where networks bite. Your plan can treat one clinic as in-network, while the hospital down the street is out-of-network, or the specialist you need is not in the network you assumed. The scary part is that you might not learn this until the claim comes back.

People also assume surprise billing is fully solved. It is improved, but there is still a major gap: ground ambulances. If you ever need an ambulance ride, you are not shopping networks from the back of a stretcher, and ground ambulance bills can still lead to out-of-network balance billing because they are not covered by the federal No Surprises Act protections. (Source: Petrie-Flom Center at Harvard Law School)

This is why “my doctor takes my insurance” is not enough. What matters is whether the plan’s network includes the places you would actually end up in real life, including urgent care options and nearby hospitals.


Prescription gaps are quiet until you hit the pharmacy counter

Prescriptions are another spot where freelancers get blindsided because the monthly premium does not tell you what the plan really does with meds. A drug can be “covered” but placed on a high tier. A medication can require prior authorization. A plan can cover a brand name only after you try a cheaper alternative first. Sometimes a deductible applies to certain prescriptions, which means you pay full price until you hit that threshold.

One useful way to think about it is this: your plan is not just a price, it is a set of rules. If you take regular medications, those rules can matter as much as the deductible. KFF’s reporting on Marketplace cost sharing and plan design consistently shows that high deductibles and other out-of-pocket costs are a major pain point for consumers, and that this pressure is especially common in lower-premium plan tiers where cost sharing is higher. (Source: KFF)

If you want fewer ugly surprises, you need the plan to match your real prescriptions, not the imaginary version of you who never needs anything.


Make your coverage match real life

If you are self-employed, the goal is not to find a perfect plan. The goal is to find a plan you can actually afford to use. That usually means looking at your likely year, then stress-testing the plan for an unlucky year. You want to know what happens if you need a specialist, a scan, and a new prescription in the same month, because that is how real life stacks bills.

If you want a calmer, guided way to compare options, you can connect with a licensed specialist through IBN360 Healthcare and narrow choices based on total cost, networks, and real-world needs, not just premium price. You can start from the main site, then explore the Blog Hub for more insights and information. If irregular income is part of your situation, this guide is a strong next read because it speaks directly to how self-employed people can choose coverage without getting overwhelmed.

Get covered with confidence through IBN360. Book a call today.

For more stories and insights, visit IBN360 Blog Hub.
health insurance for freelancers 1099 health insurance ACA marketplace deductible
Back to Blog

Member Testimonials

"Health Insurance Success Story"

Finally an affordable health insurance policy for the whole family. Independent contractors and 1099 workers are no longer out in the cold when it comes to healthcare. Be rewarded for your healthy lifestyle and tenacity to go it alone and don’t worry about premiums that drain your bank account.

"Licensed IBN360

Specialist"

I’m in awe of how simple and fast the process is to get clients price quotes and breakdown of the advantages IBN360 offers so that they can compare to their current situations. Not one has been disappointed with what they’ve heard. After a quick 10-minute information gathering, clients are set up and good to go. You can feel their sighs of relief.

"Health Insurance Success Story"

With health insurance premiums continuing to rise, I am so grateful to have found this program. Now I finally have an affordable and customizable health insurance plan for me and my family. Thank you IBN360!

"Health Insurance

Quote"

The switch to this plan saved my wife $450/mth ($5,400/yr); which also included a deductible that was $6,000 lower. Her PCP was in-network. Our family is thrilled and grateful to have such a positive financial impact.

Freelancer working on a laptop in a home office, comparing health insurance options and out-of-pocket costs.

Health Insurance for Freelancers: Why You Can Be “Covered” and Still Owe Thousands | IBN360

February 14, 2026•4 min read

You buy a plan, you pay the premium, and you breathe a little easier because you did the responsible thing. Then the first real medical moment shows up, a lab, a scan, a specialist visit, a new prescription, and the bill lands with a number that makes you check your email twice.

This is the freelancer whiplash: you are insured, but your bank account still feels uninsured. When you are a 1099 worker, you do not have HR translating the fine print, so it is easy to choose coverage that looks affordable until you actually use it.


The high deductible trap that turns “covered” into “still paying”

Most self-employed people shop by monthly premium first because that is the only number that feels stable. The problem is that many Marketplace plans push more of the cost to you up front through deductibles and coinsurance. In 2026, KFF’s analysis of Healthcare.gov plan listings finds that the average deductible across Bronze Marketplace plans is $7,476 (a simple average across available plans), and catastrophic plans generally set the deductible equal to the ACA out-of-pocket maximum, which in 2026 is $10,600 for an individual. (Source: KFF)

Here is how this usually plays out: you go to care early in the year, you have not hit the deductible, and you pay most of the bill. Even after you meet the deductible, coinsurance can keep you paying a percentage on many services until you hit the out-of-pocket maximum. That is why someone can genuinely be insured and still owe thousands, especially if they need imaging, outpatient procedures, or ongoing specialist care.


Networks matter more than people think, especially when you need care fast

Freelancers do not always have the luxury of planning care perfectly. When something hurts, you go where you can get an appointment. That is where networks bite. Your plan can treat one clinic as in-network, while the hospital down the street is out-of-network, or the specialist you need is not in the network you assumed. The scary part is that you might not learn this until the claim comes back.

People also assume surprise billing is fully solved. It is improved, but there is still a major gap: ground ambulances. If you ever need an ambulance ride, you are not shopping networks from the back of a stretcher, and ground ambulance bills can still lead to out-of-network balance billing because they are not covered by the federal No Surprises Act protections. (Source: Petrie-Flom Center at Harvard Law School)

This is why “my doctor takes my insurance” is not enough. What matters is whether the plan’s network includes the places you would actually end up in real life, including urgent care options and nearby hospitals.


Prescription gaps are quiet until you hit the pharmacy counter

Prescriptions are another spot where freelancers get blindsided because the monthly premium does not tell you what the plan really does with meds. A drug can be “covered” but placed on a high tier. A medication can require prior authorization. A plan can cover a brand name only after you try a cheaper alternative first. Sometimes a deductible applies to certain prescriptions, which means you pay full price until you hit that threshold.

One useful way to think about it is this: your plan is not just a price, it is a set of rules. If you take regular medications, those rules can matter as much as the deductible. KFF’s reporting on Marketplace cost sharing and plan design consistently shows that high deductibles and other out-of-pocket costs are a major pain point for consumers, and that this pressure is especially common in lower-premium plan tiers where cost sharing is higher. (Source: KFF)

If you want fewer ugly surprises, you need the plan to match your real prescriptions, not the imaginary version of you who never needs anything.


Make your coverage match real life

If you are self-employed, the goal is not to find a perfect plan. The goal is to find a plan you can actually afford to use. That usually means looking at your likely year, then stress-testing the plan for an unlucky year. You want to know what happens if you need a specialist, a scan, and a new prescription in the same month, because that is how real life stacks bills.

If you want a calmer, guided way to compare options, you can connect with a licensed specialist through IBN360 Healthcare and narrow choices based on total cost, networks, and real-world needs, not just premium price. You can start from the main site, then explore the Blog Hub for more insights and information. If irregular income is part of your situation, this guide is a strong next read because it speaks directly to how self-employed people can choose coverage without getting overwhelmed.

Get covered with confidence through IBN360. Book a call today.

For more stories and insights, visit IBN360 Blog Hub.
health insurance for freelancers 1099 health insurance ACA marketplace deductible
Back to Blog

Workshops

YOUR GOALS. YOUR CHOICES.

Get the Healthcare You Need at a Price That Works for You

Meet with an IBN360 specialist to learn about our healthcare network, review affordable pricing options, and get a quote based on your needs.

Workshops

YOUR GOALS. YOUR CHOICES.

Get the Healthcare You Need at a Price That Works for You

Meet with an IBN360 specialist to learn about our healthcare network, review affordable pricing options, and get a quote based on your needs.

Copyright (c) 2026 IBN360. All rights reserved

Privacy Policy I Terms and Conditions

Certain Programs and Benefits May Vary by States

IBN360 is a health coverage navigation platform. IBN360 is not a insurance carrier. All coverage discussions, quotes, and enrollments are handled by licensed specialists. Coverage availability, rates, and benefits vary by state.