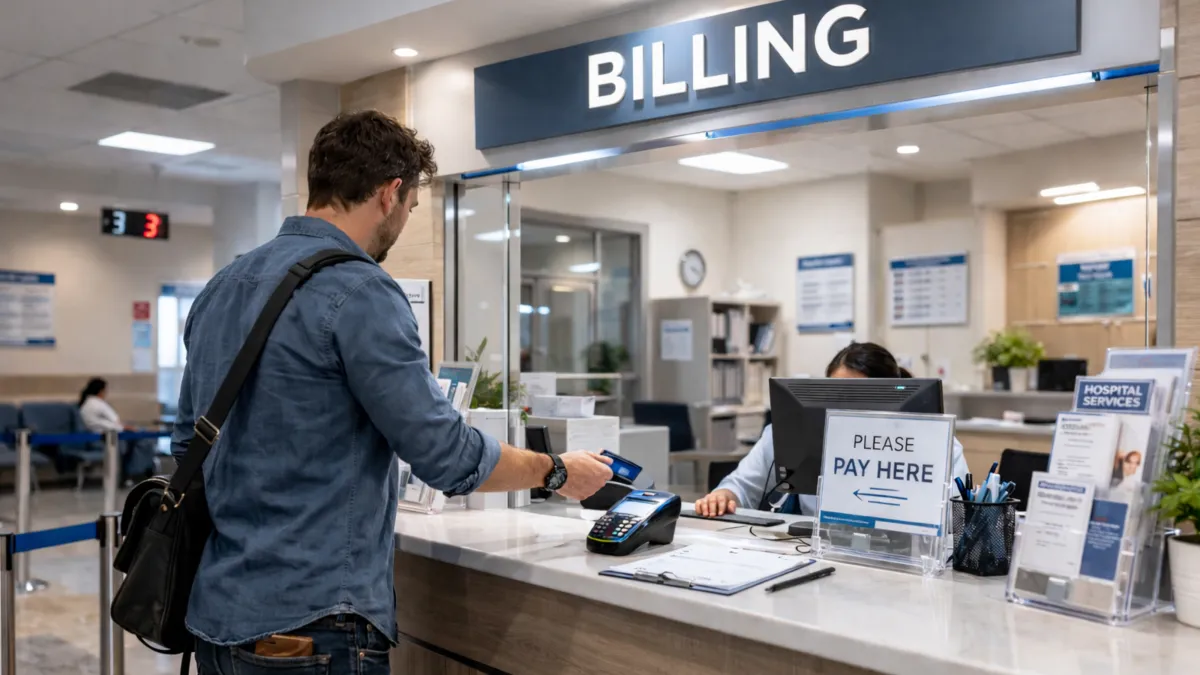
Juggling Work, Bills & Healthcare
An independent professional may be managing clients, monthly expenses, and healthcare decisions at the same time.


IBN360 helps self-employed professionals, 1099 workers, contractors, entrepreneurs, and families access affordable healthcare and other resources they need.
Explore Your Options
IBN360 helps self-employed, 1099, and independent professionals get access to healthcare, financial, protection, and business
resources they may not receive through a traditional employer.

Healthcare
Navigation
Explore healthcare resources and learn about options that may be available.

Financial
Wellness
Find resources for managing money, debt, savings, and financial goals.

Protection
Planning
Learn about protection resources and available planning options.

Business
Resources
Find information and resources for freelancers, contractors, and entrepreneurs.

Professional
Guidance
Start with a few questions and explore from there.
Explore Your Options
IBN360 helps self-employed, 1099, and independent professionals get access to healthcare, financial, protection, and business resources they may not receive through a traditional employer.

Healthcare
Navigation
Explore healthcare resources and learn about options that may be available.

Financial
Wellness
Find resources for managing money, debt, savings, and financial goals.

Protection
Planning
Learn about protection resources and available planning options.

Business
Resources
Find information and resources for freelancers, contractors, and entrepreneurs.

Professional
Guidance
Start with a few questions and explore from there.
Traditional benefits don't always work for people outside traditional employment. IBN360 provides healthcare and other resources for:
Self-employed professionals who manage their own benefits.
1099 workers and contractors who don't receive traditional employer benefits.
Freelancers and entrepreneurs who need resources that work outside a traditional workplace.
People between jobs who need another way to access healthcare.
Individuals and families looking for affordable healthcare options.
Traditional benefits don't always work for people outside traditional employment.
IBN360 provides healthcare and other resources for:
Self-employed professionals who manage their own benefits.
1099 workers and contractors who don't receive traditional employer benefits.
Freelancers and entrepreneurs who need resources that work outside a traditional workplace.
People between jobs who need another way to access healthcare.
Individuals and families looking for affordable healthcare options.
Independent work comes with a lot to manage. Here are a few everyday situations and resources you can explore through IBN360.
An independent professional may be managing clients, monthly expenses, and healthcare decisions at the same time.
Freelance and contract income can vary while bills and everyday financial responsibilities continue.
Planning for income, family responsibilities, and the future can be another thing to manage alongside work.
Business owners often balance customers, daily operations, personal finances, and other responsibilities.
Example situations are for educational and illustrative purposes only. Resources, eligibility, costs, benefits, and availability may vary.
Support that isn't tied to one employer
The way people work has changed. Benefits should work for people who are self-employed, freelance, contract, run a business, or move between jobs.
Explore: See what's available based on what you're looking for.
Learn: Understand your options in simple language.
Ask: Get additional guidance when you have questions.
Decide: Choose what makes sense for your situation.
No pressure. No complicated process.

"Health Insurance Success Story"
Finally an affordable health insurance policy for the whole family. Independent contractors and 1099 workers are no longer out in the cold when it comes to healthcare. Be rewarded for your healthy lifestyle and tenacity to go it alone and don’t worry about premiums that drain your bank account.

"Licensed IBN360
Specialist"
I’m in awe of how simple and fast the process is to get clients price quotes and breakdown of the advantages IBN360 offers so that they can compare to their current situations. Not one has been disappointed with what they’ve heard. After a quick 10-minute information gathering, clients are set up and good to go. You can feel their sighs of relief.

"Health Insurance Success Story"
With health insurance premiums continuing to rise, I am so grateful to have found this program. Now I finally have an affordable and customizable health insurance plan for me and my family. Thank you IBN360!

"Health Insurance
Quote"
The switch to this plan saved my wife $450/mth ($5,400/yr); which also included a deductible that was $6,000 lower. Her PCP was in-network. Our family is thrilled and grateful to have such a positive financial impact.

You do not need a “major” medical event for medical debt to show up. Sometimes, it's one ER visit after a bad fever, one imaging bill you thought was covered, or one outpatient procedure that turns into three separate charges you did not expect.
And once that first bill hits, it can quietly take over your year. You start juggling rent, groceries, and minimum payments. You delay follow-up care. You keep telling yourself you will catch up next month, but the numbers keep moving.
A lot of people picture medical debt as one unpaid invoice. In real life, it often becomes a chain reaction. A bill gets split across multiple providers. A payment plan starts. Then the gap gets covered with a credit card, and the balance sticks around because interest does not take a break.
That is why medical debt is so common even among people who are working and trying to stay responsible. One 2025 analysis found that when “medical debt” is defined broadly, it includes things like past-due bills, paying providers over time, and using loans or revolving credit to cover care, which helps explain why so many households get pulled into it. (Source: Health Affairs Scholar)
Medical debt is not just a healthcare problem. It becomes a housing and stability problem fast. When you are already living on a tight monthly margin, a surprise bill does not just hurt, it forces tradeoffs. People cut essentials first because they are trying to stay afloat.
A 2026 Johns Hopkins report on research published in JAMA Network Open links medical debt with later difficulty paying rent or a mortgage, and it notes renters were disproportionately affected, making up a large share of adults with medical debt in 2025. That lines up with what many families feel right now: one unexpected expense can shove everything else out of place. (Source: Johns Hopkins Bloomberg School of Public Health)
This is where people feel blindsided. You can have coverage and still face a bill that is big enough to trigger that domino effect. The reason is usually cost-sharing: deductibles, coinsurance, and out-of-pocket maximums that are higher than people realize until they actually need care.
For 2026, KFF points out just how high the ceiling can be, including an ACA out-of-pocket maximum of $10,600 for an individual and $21,200 for a family, plus high deductibles in many plan tiers. If your plan design pushes a lot of costs to the front end of the year, one hospital visit can land at the worst possible time, especially for independent workers whose income can swing month to month. (Source: KFF)
If you are self-employed, between jobs, or doing 1099 work, the goal is not to pick a plan that only looks good on paper. It is to pick coverage that you can actually use without getting wrecked by the first serious bill. That usually means slowing down and comparing the parts that control your risk, like how the deductible works, what your out-of-pocket limit is, and how your plan handles the types of care you are most likely to need.
This is exactly where IBN360 comes in as a practical guide, because the company is built around helping independent workers, part-timers, and in between jobs sort through options with licensed specialist support and a focus on balancing monthly cost, deductible exposure, and real-world care needs. If you are trying to avoid the medical-debt trap, getting clear on those tradeoffs before you enroll is one of the cleanest ways to protect your year.
The point is not to predict every medical scenario. It is to stop one bill from turning into six months of stress. If you want help making sense of your options, IBN360 can walk you through what may fit your situation and help you compare choices in a way that feels calm and clear. You can also check the IBN360 Blog Hub for more guides and insights like this, then head to the IBN360 appointment page to set up an appointment with one of the specialists when you are ready.
Make your next step simple. Book an IBN360 call.
"Health Insurance Success Story"
Finally an affordable health insurance policy for the whole family. Independent contractors and 1099 workers are no longer out in the cold when it comes to healthcare. Be rewarded for your healthy lifestyle and tenacity to go it alone and don’t worry about premiums that drain your bank account.

"Licensed IBN360
Specialist"
I’m in awe of how simple and fast the process is to get clients price quotes and breakdown of the advantages IBN360 offers so that they can compare to their current situations. Not one has been disappointed with what they’ve heard. After a quick 10-minute information gathering, clients are set up and good to go. You can feel their sighs of relief.

"Health Insurance Success Story"
With health insurance premiums continuing to rise, I am so grateful to have found this program. Now I finally have an affordable and customizable health insurance plan for me and my family. Thank you IBN360!

"Health Insurance
Quote"
The switch to this plan saved my wife $450/mth ($5,400/yr); which also included a deductible that was $6,000 lower. Her PCP was in-network. Our family is thrilled and grateful to have such a positive financial impact.

You do not need a “major” medical event for medical debt to show up. Sometimes, it's one ER visit after a bad fever, one imaging bill you thought was covered, or one outpatient procedure that turns into three separate charges you did not expect.
And once that first bill hits, it can quietly take over your year. You start juggling rent, groceries, and minimum payments. You delay follow-up care. You keep telling yourself you will catch up next month, but the numbers keep moving.
A lot of people picture medical debt as one unpaid invoice. In real life, it often becomes a chain reaction. A bill gets split across multiple providers. A payment plan starts. Then the gap gets covered with a credit card, and the balance sticks around because interest does not take a break.
That is why medical debt is so common even among people who are working and trying to stay responsible. One 2025 analysis found that when “medical debt” is defined broadly, it includes things like past-due bills, paying providers over time, and using loans or revolving credit to cover care, which helps explain why so many households get pulled into it. (Source: Health Affairs Scholar)
Medical debt is not just a healthcare problem. It becomes a housing and stability problem fast. When you are already living on a tight monthly margin, a surprise bill does not just hurt, it forces tradeoffs. People cut essentials first because they are trying to stay afloat.
A 2026 Johns Hopkins report on research published in JAMA Network Open links medical debt with later difficulty paying rent or a mortgage, and it notes renters were disproportionately affected, making up a large share of adults with medical debt in 2025. That lines up with what many families feel right now: one unexpected expense can shove everything else out of place. (Source: Johns Hopkins Bloomberg School of Public Health)
This is where people feel blindsided. You can have coverage and still face a bill that is big enough to trigger that domino effect. The reason is usually cost-sharing: deductibles, coinsurance, and out-of-pocket maximums that are higher than people realize until they actually need care.
For 2026, KFF points out just how high the ceiling can be, including an ACA out-of-pocket maximum of $10,600 for an individual and $21,200 for a family, plus high deductibles in many plan tiers. If your plan design pushes a lot of costs to the front end of the year, one hospital visit can land at the worst possible time, especially for independent workers whose income can swing month to month. (Source: KFF)
If you are self-employed, between jobs, or doing 1099 work, the goal is not to pick a plan that only looks good on paper. It is to pick coverage that you can actually use without getting wrecked by the first serious bill. That usually means slowing down and comparing the parts that control your risk, like how the deductible works, what your out-of-pocket limit is, and how your plan handles the types of care you are most likely to need.
This is exactly where IBN360 comes in as a practical guide, because the company is built around helping independent workers, part-timers, and in between jobs sort through options with licensed specialist support and a focus on balancing monthly cost, deductible exposure, and real-world care needs. If you are trying to avoid the medical-debt trap, getting clear on those tradeoffs before you enroll is one of the cleanest ways to protect your year.
The point is not to predict every medical scenario. It is to stop one bill from turning into six months of stress. If you want help making sense of your options, IBN360 can walk you through what may fit your situation and help you compare choices in a way that feels calm and clear. You can also check the IBN360 Blog Hub for more guides and insights like this, then head to the IBN360 appointment page to set up an appointment with one of the specialists when you are ready.
Make your next step simple. Book an IBN360 call.
YOUR GOALS. YOUR CHOICES.
Get the Healthcare You Need at a Price That Works for You
Meet with an IBN360 specialist to learn about our healthcare network, review affordable pricing options, and get a quote based on your needs.
YOUR GOALS. YOUR CHOICES.
Get the Healthcare You Need at a Price That Works for You
Meet with an IBN360 specialist to learn about our healthcare network, review affordable pricing options, and get a quote based on your needs.

Copyright (c) 2026 IBN360. All rights reserved
Certain Programs and Benefits May Vary by States
IBN360 is a health coverage navigation platform. IBN360 is not a insurance carrier. All coverage discussions, quotes, and enrollments are handled by licensed specialists. Coverage availability, rates, and benefits vary by state.