or call 1 888-378-9012

or call 1 888-378-9012

Get Quality Healthcare Without overspending

IBN360 helps self-employed professionals, 1099 workers, contractors, entrepreneurs, and families access affordable healthcare and other resources they need.

Get Quality Healthcare Without overspending

IBN360 helps self-employed professionals, 1099 workers, contractors, entrepreneurs, and families access affordable healthcare and other resources they need.

Explore Your Options

A Complete Solution for

Healthcare and More

IBN360 helps self-employed, 1099, and independent professionals get access to healthcare, financial, protection, and business

resources they may not receive through a traditional employer.

Healthcare

Navigation

Explore healthcare resources and learn about options that may be available.

Financial

Wellness

Find resources for managing money, debt, savings, and financial goals.

Protection

Planning

Learn about protection resources and available planning options.

Business

Resources

Find information and resources for freelancers, contractors, and entrepreneurs.

Professional

Guidance

Start with a few questions and explore from there.

Explore Your Options

A Complete Solution for

Healthcare and More

IBN360 helps self-employed, 1099, and independent professionals get access to healthcare, financial, protection, and business resources they may not receive through a traditional employer.

Healthcare

Navigation

Explore healthcare resources and learn about options that may be available.

Financial

Wellness

Find resources for managing money, debt, savings, and financial goals.

Protection

Planning

Learn about protection resources and available planning options.

Business

Resources

Find information and resources for freelancers, contractors, and entrepreneurs.

Professional

Guidance

Start with a few questions and explore from there.

Built for people who work differently

Traditional benefits don't always work for people outside traditional employment. IBN360 provides healthcare and other resources for:

  • Self-employed professionals who manage their own benefits.

  • 1099 workers and contractors who don't receive traditional employer benefits.

  • Freelancers and entrepreneurs who need resources that work outside a traditional workplace.

  • People between jobs who need another way to access healthcare.

  • Individuals and families looking for affordable healthcare options.

Built for people who work differently

Traditional benefits don't always work for people outside traditional employment.

IBN360 provides healthcare and other resources for:

  • Self-employed professionals who manage their own benefits.

  • 1099 workers and contractors who don't receive traditional employer benefits.

  • Freelancers and entrepreneurs who need resources that work outside a traditional workplace.

  • People between jobs who need another way to access healthcare.

  • Individuals and families looking for affordable healthcare options.

REAL-LIFE SITUATIONS

WHERE IBN360
FITS

Independent work comes with a lot to manage. Here are a few everyday situations and resources you can explore through IBN360.

01

Juggling Work, Bills & Healthcare

An independent professional may be managing clients, monthly expenses, and healthcare decisions at the same time.

Explore: Healthcare navigation and educational resources.
02

Managing an Income That Changes

Freelance and contract income can vary while bills and everyday financial responsibilities continue.

Explore: Budgeting, saving, debt, and financial wellness resources.
03

Thinking About What Comes Next

Planning for income, family responsibilities, and the future can be another thing to manage alongside work.

Explore: Protection planning information and educational resources.
04

Running a Business & Managing Life

Business owners often balance customers, daily operations, personal finances, and other responsibilities.

Explore: Business and independent professional resources.

Example situations are for educational and illustrative purposes only. Resources, eligibility, costs, benefits, and availability may vary.

Workshops

Support that isn't tied to one employer

The way people work has changed. Benefits should work for people who are self-employed, freelance, contract, run a business, or move between jobs.

  • Explore: See what's available based on what you're looking for.

  • Learn: Understand your options in simple language.

  • Ask: Get additional guidance when you have questions.

  • Decide: Choose what makes sense for your situation.

No pressure. No complicated process.

Member Testimonials

"Health Insurance Success Story"

Finally an affordable health insurance policy for the whole family. Independent contractors and 1099 workers are no longer out in the cold when it comes to healthcare. Be rewarded for your healthy lifestyle and tenacity to go it alone and don’t worry about premiums that drain your bank account.

"Licensed IBN360

Specialist"

I’m in awe of how simple and fast the process is to get clients price quotes and breakdown of the advantages IBN360 offers so that they can compare to their current situations. Not one has been disappointed with what they’ve heard. After a quick 10-minute information gathering, clients are set up and good to go. You can feel their sighs of relief.

"Health Insurance Success Story"

With health insurance premiums continuing to rise, I am so grateful to have found this program. Now I finally have an affordable and customizable health insurance plan for me and my family. Thank you IBN360!

"Health Insurance

Quote"

The switch to this plan saved my wife $450/mth ($5,400/yr); which also included a deductible that was $6,000 lower. Her PCP was in-network. Our family is thrilled and grateful to have such a positive financial impact.

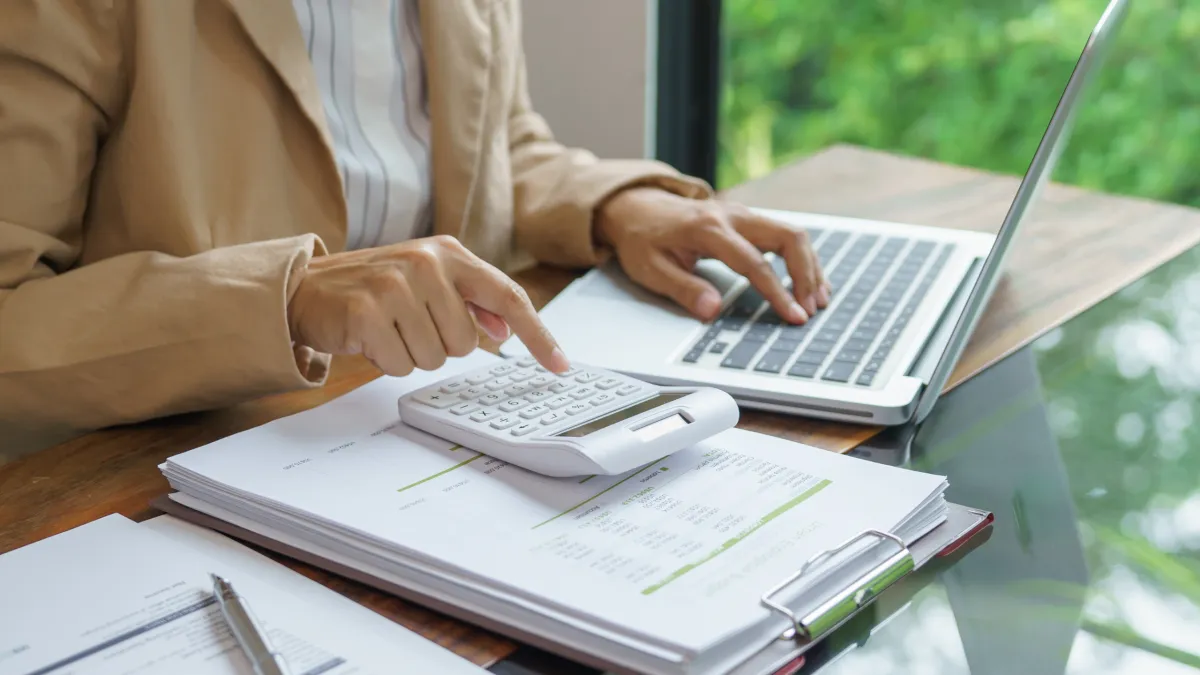
Freelancer reviewing expenses with a calculator and laptop

How to Budget as a Freelancer Without a Regular Paycheck | IBN360

June 22, 2026•3 min read

A freelancer can finish a strong project in March, wait weeks for payment, and enter April with less cash than expected. Rent, groceries, insurance, software subscriptions, and credit card payments still arrive on schedule. This gap between earning money and receiving it makes a paycheck-based budget difficult to use.

A practical freelancer budget should keep the same basic structure even when monthly income changes. The goal is to create a steady system for bills, taxes, business costs, savings, and slower periods.


Build Your Budget Around a Dependable Baseline

Review six to twelve months of deposits and identify a conservative monthly income level. Use a lower-earning month or the average of several slower months for regular commitments. Housing, utilities, groceries, transportation, insurance, minimum debt payments, and other essentials should fit within that amount.

The Federal Reserve’s Report on the Economic Well-Being of U.S. Households in 2025 shows why this matters. Among self-employed adults, 58% said their income varied from month to month. Twenty-two percent struggled to pay bills during the previous year because their income varied. (Source: Federal Reserve)

Once the baseline is set, income above it can support upcoming costs, savings goals, and slower months without permanently increasing regular spending.


Separate Business Money and Set Aside Taxes Early

Freelance revenue may need to cover personal spending, taxes, and business expenses. Keeping everything in one checking account can make the available balance appear larger than the amount that is free to spend.

A separate business account can make deposits and expenses easier to track. A dedicated tax savings account can also reduce the risk of spending money that will be needed later. Transfer a consistent percentage from each payment, then review it with a qualified tax professional. The amount depends on earnings, deductions, filing status, and state taxes.

The IRS explains that self-employed individuals generally file an annual income tax return and may need to make estimated tax payments during the year. These payments can cover income tax and self-employment tax when taxes are not withheld from earnings. (Source: Internal Revenue Service)

After setting aside taxes, plan for business costs such as software, equipment, professional services, payment processing fees, and insurance.


Use Strong Months to Prepare for Slower Ones

After covering current expenses and taxes, direct part of a strong month’s remaining income to a slow-month fund. This money can help pay normal bills when projects pause, invoices arrive late, or a client reduces work.

Begin with a target of one month of essential expenses, then build from there. The Federal Reserve reported that 63% of U.S. adults could cover a $400 emergency using cash, savings, or a credit card paid off at the next statement. Twelve percent said they could not cover the expense through any method. (Source: Federal Reserve)

Freelancers may also need separate savings for predictable costs such as software renewals, vehicle repairs, health care, and quarterly insurance premiums. Saving throughout the year keeps these expenses from disrupting the regular budget.


Make the Budget Easy to Update

Choose one time each month to review payments received, unpaid invoices, upcoming expenses, tax savings, and the slow-month fund. Adjust flexible spending based on cash already received instead of income that is still expected.

A useful budget should show what must be paid, what is reserved, and how long available cash can support the next stretch of work. IBN360 offers financial wellness resources, protection guidance, and business support for independent professionals.

Explore the IBN360 platform, read more practical guidance in the IBN360 Blog Hub, or schedule a conversation to learn about available resources for your situation.

Budget with purpose. Grow with IBN360.
How to budget as a freelancerFreelancer budgetBudgeting with irregular income
Back to Blog

Member Testimonials

"Health Insurance Success Story"

Finally an affordable health insurance policy for the whole family. Independent contractors and 1099 workers are no longer out in the cold when it comes to healthcare. Be rewarded for your healthy lifestyle and tenacity to go it alone and don’t worry about premiums that drain your bank account.

"Licensed IBN360

Specialist"

I’m in awe of how simple and fast the process is to get clients price quotes and breakdown of the advantages IBN360 offers so that they can compare to their current situations. Not one has been disappointed with what they’ve heard. After a quick 10-minute information gathering, clients are set up and good to go. You can feel their sighs of relief.

"Health Insurance Success Story"

With health insurance premiums continuing to rise, I am so grateful to have found this program. Now I finally have an affordable and customizable health insurance plan for me and my family. Thank you IBN360!

"Health Insurance

Quote"

The switch to this plan saved my wife $450/mth ($5,400/yr); which also included a deductible that was $6,000 lower. Her PCP was in-network. Our family is thrilled and grateful to have such a positive financial impact.

Freelancer reviewing expenses with a calculator and laptop

How to Budget as a Freelancer Without a Regular Paycheck | IBN360

June 22, 2026•3 min read

A freelancer can finish a strong project in March, wait weeks for payment, and enter April with less cash than expected. Rent, groceries, insurance, software subscriptions, and credit card payments still arrive on schedule. This gap between earning money and receiving it makes a paycheck-based budget difficult to use.

A practical freelancer budget should keep the same basic structure even when monthly income changes. The goal is to create a steady system for bills, taxes, business costs, savings, and slower periods.


Build Your Budget Around a Dependable Baseline

Review six to twelve months of deposits and identify a conservative monthly income level. Use a lower-earning month or the average of several slower months for regular commitments. Housing, utilities, groceries, transportation, insurance, minimum debt payments, and other essentials should fit within that amount.

The Federal Reserve’s Report on the Economic Well-Being of U.S. Households in 2025 shows why this matters. Among self-employed adults, 58% said their income varied from month to month. Twenty-two percent struggled to pay bills during the previous year because their income varied. (Source: Federal Reserve)

Once the baseline is set, income above it can support upcoming costs, savings goals, and slower months without permanently increasing regular spending.


Separate Business Money and Set Aside Taxes Early

Freelance revenue may need to cover personal spending, taxes, and business expenses. Keeping everything in one checking account can make the available balance appear larger than the amount that is free to spend.

A separate business account can make deposits and expenses easier to track. A dedicated tax savings account can also reduce the risk of spending money that will be needed later. Transfer a consistent percentage from each payment, then review it with a qualified tax professional. The amount depends on earnings, deductions, filing status, and state taxes.

The IRS explains that self-employed individuals generally file an annual income tax return and may need to make estimated tax payments during the year. These payments can cover income tax and self-employment tax when taxes are not withheld from earnings. (Source: Internal Revenue Service)

After setting aside taxes, plan for business costs such as software, equipment, professional services, payment processing fees, and insurance.


Use Strong Months to Prepare for Slower Ones

After covering current expenses and taxes, direct part of a strong month’s remaining income to a slow-month fund. This money can help pay normal bills when projects pause, invoices arrive late, or a client reduces work.

Begin with a target of one month of essential expenses, then build from there. The Federal Reserve reported that 63% of U.S. adults could cover a $400 emergency using cash, savings, or a credit card paid off at the next statement. Twelve percent said they could not cover the expense through any method. (Source: Federal Reserve)

Freelancers may also need separate savings for predictable costs such as software renewals, vehicle repairs, health care, and quarterly insurance premiums. Saving throughout the year keeps these expenses from disrupting the regular budget.


Make the Budget Easy to Update

Choose one time each month to review payments received, unpaid invoices, upcoming expenses, tax savings, and the slow-month fund. Adjust flexible spending based on cash already received instead of income that is still expected.

A useful budget should show what must be paid, what is reserved, and how long available cash can support the next stretch of work. IBN360 offers financial wellness resources, protection guidance, and business support for independent professionals.

Explore the IBN360 platform, read more practical guidance in the IBN360 Blog Hub, or schedule a conversation to learn about available resources for your situation.

Budget with purpose. Grow with IBN360.
How to budget as a freelancerFreelancer budgetBudgeting with irregular income
Back to Blog

Workshops

YOUR GOALS. YOUR CHOICES.

Get the Healthcare You Need at a Price That Works for You

Meet with an IBN360 specialist to learn about our healthcare network, review affordable pricing options, and get a quote based on your needs.

Workshops

YOUR GOALS. YOUR CHOICES.

Get the Healthcare You Need at a Price That Works for You

Meet with an IBN360 specialist to learn about our healthcare network, review affordable pricing options, and get a quote based on your needs.

Copyright (c) 2026 IBN360. All rights reserved

Privacy Policy I Terms and Conditions

Certain Programs and Benefits May Vary by States

IBN360 is a health coverage navigation platform. IBN360 is not a insurance carrier. All coverage discussions, quotes, and enrollments are handled by licensed specialists. Coverage availability, rates, and benefits vary by state.