Juggling Work, Bills & Healthcare
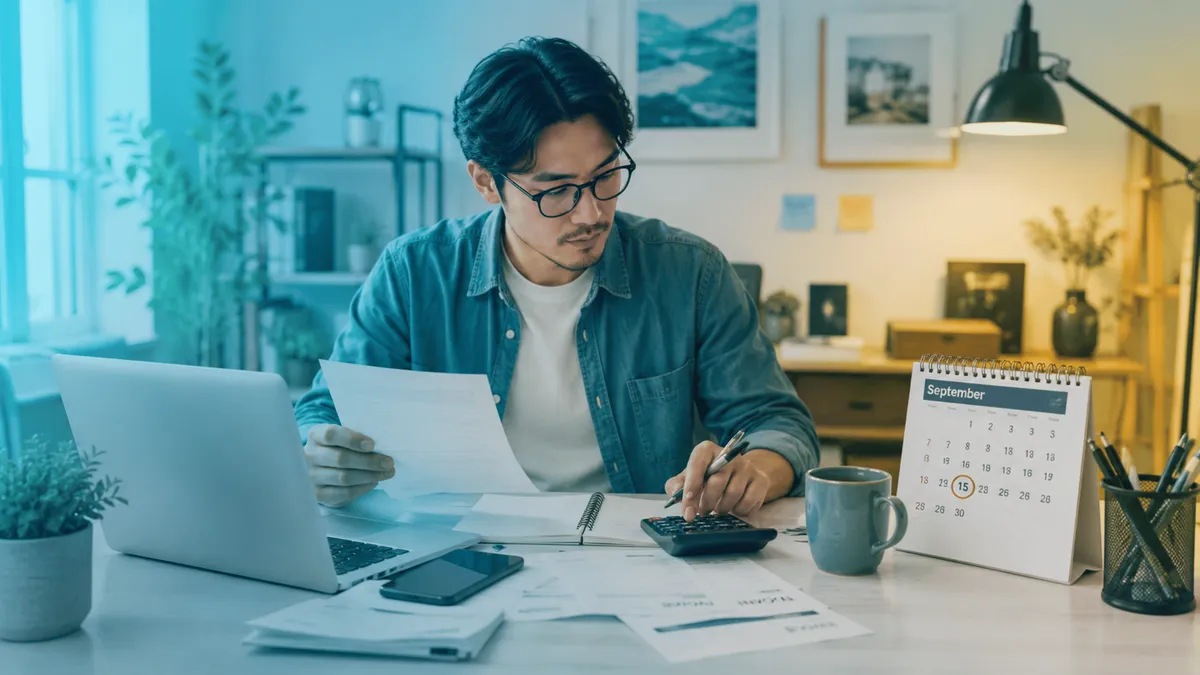
An independent professional may be managing clients, monthly expenses, and healthcare decisions at the same time.


IBN360 helps self-employed professionals, 1099 workers, contractors, entrepreneurs, and families access affordable healthcare and other resources they need.
Explore Your Options
IBN360 helps self-employed, 1099, and independent professionals get access to healthcare, financial, protection, and business
resources they may not receive through a traditional employer.

Healthcare
Navigation
Explore healthcare resources and learn about options that may be available.

Financial
Wellness
Find resources for managing money, debt, savings, and financial goals.

Protection
Planning
Learn about protection resources and available planning options.

Business
Resources
Find information and resources for freelancers, contractors, and entrepreneurs.

Professional
Guidance
Start with a few questions and explore from there.
Explore Your Options
IBN360 helps self-employed, 1099, and independent professionals get access to healthcare, financial, protection, and business resources they may not receive through a traditional employer.

Healthcare
Navigation
Explore healthcare resources and learn about options that may be available.

Financial
Wellness
Find resources for managing money, debt, savings, and financial goals.

Protection
Planning
Learn about protection resources and available planning options.

Business
Resources
Find information and resources for freelancers, contractors, and entrepreneurs.

Professional
Guidance
Start with a few questions and explore from there.
Traditional benefits don't always work for people outside traditional employment. IBN360 provides healthcare and other resources for:
Self-employed professionals who manage their own benefits.
1099 workers and contractors who don't receive traditional employer benefits.
Freelancers and entrepreneurs who need resources that work outside a traditional workplace.
People between jobs who need another way to access healthcare.
Individuals and families looking for affordable healthcare options.
Traditional benefits don't always work for people outside traditional employment.
IBN360 provides healthcare and other resources for:
Self-employed professionals who manage their own benefits.
1099 workers and contractors who don't receive traditional employer benefits.
Freelancers and entrepreneurs who need resources that work outside a traditional workplace.
People between jobs who need another way to access healthcare.
Individuals and families looking for affordable healthcare options.
Independent work comes with a lot to manage. Here are a few everyday situations and resources you can explore through IBN360.
An independent professional may be managing clients, monthly expenses, and healthcare decisions at the same time.
Freelance and contract income can vary while bills and everyday financial responsibilities continue.
Planning for income, family responsibilities, and the future can be another thing to manage alongside work.
Business owners often balance customers, daily operations, personal finances, and other responsibilities.
Example situations are for educational and illustrative purposes only. Resources, eligibility, costs, benefits, and availability may vary.
Support that isn't tied to one employer
The way people work has changed. Benefits should work for people who are self-employed, freelance, contract, run a business, or move between jobs.
Explore: See what's available based on what you're looking for.
Learn: Understand your options in simple language.
Ask: Get additional guidance when you have questions.
Decide: Choose what makes sense for your situation.
No pressure. No complicated process.

"Health Insurance Success Story"
Finally an affordable health insurance policy for the whole family. Independent contractors and 1099 workers are no longer out in the cold when it comes to healthcare. Be rewarded for your healthy lifestyle and tenacity to go it alone and don’t worry about premiums that drain your bank account.

"Licensed IBN360
Specialist"
I’m in awe of how simple and fast the process is to get clients price quotes and breakdown of the advantages IBN360 offers so that they can compare to their current situations. Not one has been disappointed with what they’ve heard. After a quick 10-minute information gathering, clients are set up and good to go. You can feel their sighs of relief.

"Health Insurance Success Story"
With health insurance premiums continuing to rise, I am so grateful to have found this program. Now I finally have an affordable and customizable health insurance plan for me and my family. Thank you IBN360!

"Health Insurance
Quote"
The switch to this plan saved my wife $450/mth ($5,400/yr); which also included a deductible that was $6,000 lower. Her PCP was in-network. Our family is thrilled and grateful to have such a positive financial impact.

A regular paycheck usually comes with one useful feature: taxes are taken out before the money reaches your bank account. For freelancers, independent contractors, and other 1099 workers, that withholding often does not happen automatically. If you earn income without enough tax being withheld, you may need to make estimated tax payments during the year.
That makes September 15 worth putting on the calendar. For calendar-year taxpayers, September 15, 2026 is the third general federal estimated-tax payment due date. The more important question is whether you need to pay and how much. For the independent professionals IBN360 serves, the answer can depend on expected tax, prior-year tax, withholding, credits, and when income arrived.
For federal estimated taxes, the IRS divides the calendar year into four payment periods. The third 2026 period generally covers income received from June 1 through August 31, with payment due September 15. The fourth period runs from September 1 through December 31, with payment generally due January 15, 2027. State estimated-tax deadlines and calculation rules may differ. (Source: Internal Revenue Service)
Estimated tax is part of the federal pay-as-you-go system. It allows people with income that is not fully covered by withholding to pay tax during the year. Paying too little or paying late can lead to an underpayment penalty, even when the remaining tax is eventually paid with the return. (Source: Internal Revenue Service)
Being a 1099 worker does not automatically mean a September payment is required. In most cases, the IRS requires estimated tax payments for 2026 when both conditions apply: you expect to owe at least $1,000 after subtracting withholding and refundable credits, and those amounts will cover less than the smaller of 90% of your 2026 tax or 100% of the tax shown on a full 12-month 2025 return.
A separate exception may apply if you were a U.S. citizen or resident alien for all of 2025 and had no 2025 tax liability.
For certain higher-income taxpayers, the prior-year percentage rises to 110%. That generally applies when 2025 adjusted gross income exceeded $150,000, or $75,000 for someone married filing separately. Special rules apply to farmers, fishers, and some other taxpayers. (Source: Internal Revenue Service)
Imagine a freelance designer with no withholding who expects total 2026 tax of $18,000 and had $12,000 of tax on a full-year 2025 return. Because 90% of $18,000 is $16,200, the smaller annual target is $12,000. Under the regular installment method, that generally means four $3,000 payments.
If $3,000 was paid in April and June, another $3,000 would generally be due September 15. A missed earlier installment can still create a penalty for that earlier period.
A strong summer can raise the final 2026 tax bill above the prior-year figure. The 2025 tax remains relevant because it helps establish the required annual payment used to avoid an underpayment penalty. Estimated payments may cover federal income tax and self-employment tax.
Freelance income rarely arrives in four tidy pieces. Someone might earn $2,500 one month, $8,000 the next, and considerably less after a contract ends. Four equal payments may not reflect that pattern.
The IRS allows eligible taxpayers with uneven income to use the annualized income installment method. It uses income, deductions, and other relevant items measured through each payment period, allowing the required installments to reflect an uneven earning pattern.
Taxpayers using this method generally must file Form 2210, including Schedule AI, with their 2026 return.
Specific IRS worksheets control the calculation, so a slower month alone does not erase a required payment. Because underpayment is evaluated by payment period, income timing can change the required installment.
Review year-to-date income and business expenses, the 2025 tax return, expected income and deductions, withholding, and prior estimated payments.
The 2026 Form 1040-ES contains the worksheet used to estimate the required annual payment. Federal payments can be made through IRS Direct Pay, an IRS Online Account, EFTPS, or a Form 1040-ES voucher. Uneven income or unclear safe-harbor rules may warrant help from a qualified tax professional.
Tax planning is only one part of managing independent income. IBN360’s guide to budgeting as a freelancer without a regular paycheck provides a broader framework for taxes, business expenses, savings, and slower months.
IBN360 offers financial wellness tools and educational resources for independent professionals. Explore IBN360’s financial wellness resources when building a system around variable income. Questions about individual tax calculations should go to a qualified tax professional.
Grow with confidence through IBN360.
Disclaimer: This article is for general educational purposes and is not tax, legal, or financial advice. Tax obligations vary based on individual circumstances.
"Health Insurance Success Story"
Finally an affordable health insurance policy for the whole family. Independent contractors and 1099 workers are no longer out in the cold when it comes to healthcare. Be rewarded for your healthy lifestyle and tenacity to go it alone and don’t worry about premiums that drain your bank account.

"Licensed IBN360
Specialist"
I’m in awe of how simple and fast the process is to get clients price quotes and breakdown of the advantages IBN360 offers so that they can compare to their current situations. Not one has been disappointed with what they’ve heard. After a quick 10-minute information gathering, clients are set up and good to go. You can feel their sighs of relief.

"Health Insurance Success Story"
With health insurance premiums continuing to rise, I am so grateful to have found this program. Now I finally have an affordable and customizable health insurance plan for me and my family. Thank you IBN360!

"Health Insurance
Quote"
The switch to this plan saved my wife $450/mth ($5,400/yr); which also included a deductible that was $6,000 lower. Her PCP was in-network. Our family is thrilled and grateful to have such a positive financial impact.

A regular paycheck usually comes with one useful feature: taxes are taken out before the money reaches your bank account. For freelancers, independent contractors, and other 1099 workers, that withholding often does not happen automatically. If you earn income without enough tax being withheld, you may need to make estimated tax payments during the year.
That makes September 15 worth putting on the calendar. For calendar-year taxpayers, September 15, 2026 is the third general federal estimated-tax payment due date. The more important question is whether you need to pay and how much. For the independent professionals IBN360 serves, the answer can depend on expected tax, prior-year tax, withholding, credits, and when income arrived.
For federal estimated taxes, the IRS divides the calendar year into four payment periods. The third 2026 period generally covers income received from June 1 through August 31, with payment due September 15. The fourth period runs from September 1 through December 31, with payment generally due January 15, 2027. State estimated-tax deadlines and calculation rules may differ. (Source: Internal Revenue Service)
Estimated tax is part of the federal pay-as-you-go system. It allows people with income that is not fully covered by withholding to pay tax during the year. Paying too little or paying late can lead to an underpayment penalty, even when the remaining tax is eventually paid with the return. (Source: Internal Revenue Service)
Being a 1099 worker does not automatically mean a September payment is required. In most cases, the IRS requires estimated tax payments for 2026 when both conditions apply: you expect to owe at least $1,000 after subtracting withholding and refundable credits, and those amounts will cover less than the smaller of 90% of your 2026 tax or 100% of the tax shown on a full 12-month 2025 return.
A separate exception may apply if you were a U.S. citizen or resident alien for all of 2025 and had no 2025 tax liability.
For certain higher-income taxpayers, the prior-year percentage rises to 110%. That generally applies when 2025 adjusted gross income exceeded $150,000, or $75,000 for someone married filing separately. Special rules apply to farmers, fishers, and some other taxpayers. (Source: Internal Revenue Service)
Imagine a freelance designer with no withholding who expects total 2026 tax of $18,000 and had $12,000 of tax on a full-year 2025 return. Because 90% of $18,000 is $16,200, the smaller annual target is $12,000. Under the regular installment method, that generally means four $3,000 payments.
If $3,000 was paid in April and June, another $3,000 would generally be due September 15. A missed earlier installment can still create a penalty for that earlier period.
A strong summer can raise the final 2026 tax bill above the prior-year figure. The 2025 tax remains relevant because it helps establish the required annual payment used to avoid an underpayment penalty. Estimated payments may cover federal income tax and self-employment tax.
Freelance income rarely arrives in four tidy pieces. Someone might earn $2,500 one month, $8,000 the next, and considerably less after a contract ends. Four equal payments may not reflect that pattern.
The IRS allows eligible taxpayers with uneven income to use the annualized income installment method. It uses income, deductions, and other relevant items measured through each payment period, allowing the required installments to reflect an uneven earning pattern.
Taxpayers using this method generally must file Form 2210, including Schedule AI, with their 2026 return.
Specific IRS worksheets control the calculation, so a slower month alone does not erase a required payment. Because underpayment is evaluated by payment period, income timing can change the required installment.
Review year-to-date income and business expenses, the 2025 tax return, expected income and deductions, withholding, and prior estimated payments.
The 2026 Form 1040-ES contains the worksheet used to estimate the required annual payment. Federal payments can be made through IRS Direct Pay, an IRS Online Account, EFTPS, or a Form 1040-ES voucher. Uneven income or unclear safe-harbor rules may warrant help from a qualified tax professional.
Tax planning is only one part of managing independent income. IBN360’s guide to budgeting as a freelancer without a regular paycheck provides a broader framework for taxes, business expenses, savings, and slower months.
IBN360 offers financial wellness tools and educational resources for independent professionals. Explore IBN360’s financial wellness resources when building a system around variable income. Questions about individual tax calculations should go to a qualified tax professional.
Grow with confidence through IBN360.
Disclaimer: This article is for general educational purposes and is not tax, legal, or financial advice. Tax obligations vary based on individual circumstances.
YOUR GOALS. YOUR CHOICES.
Get the Healthcare You Need at a Price That Works for You
Meet with an IBN360 specialist to learn about our healthcare network, review affordable pricing options, and get a quote based on your needs.
YOUR GOALS. YOUR CHOICES.
Get the Healthcare You Need at a Price That Works for You
Meet with an IBN360 specialist to learn about our healthcare network, review affordable pricing options, and get a quote based on your needs.

Copyright (c) 2026 IBN360. All rights reserved
Certain Programs and Benefits May Vary by States
IBN360 is a health coverage navigation platform. IBN360 is not a insurance carrier. All coverage discussions, quotes, and enrollments are handled by licensed specialists. Coverage availability, rates, and benefits vary by state.