or call 1 888-378-9012

or call 1 888-378-9012

Get Quality Healthcare Without overspending

IBN360 helps self-employed professionals, 1099 workers, contractors, entrepreneurs, and families access affordable healthcare and other resources they need.

Get Quality Healthcare Without overspending

IBN360 helps self-employed professionals, 1099 workers, contractors, entrepreneurs, and families access affordable healthcare and other resources they need.

Explore Your Options

A Complete Solution for

Healthcare and More

IBN360 helps self-employed, 1099, and independent professionals get access to healthcare, financial, protection, and business

resources they may not receive through a traditional employer.

Healthcare

Navigation

Explore healthcare resources and learn about options that may be available.

Financial

Wellness

Find resources for managing money, debt, savings, and financial goals.

Protection

Planning

Learn about protection resources and available planning options.

Business

Resources

Find information and resources for freelancers, contractors, and entrepreneurs.

Professional

Guidance

Start with a few questions and explore from there.

Explore Your Options

A Complete Solution for

Healthcare and More

IBN360 helps self-employed, 1099, and independent professionals get access to healthcare, financial, protection, and business resources they may not receive through a traditional employer.

Healthcare

Navigation

Explore healthcare resources and learn about options that may be available.

Financial

Wellness

Find resources for managing money, debt, savings, and financial goals.

Protection

Planning

Learn about protection resources and available planning options.

Business

Resources

Find information and resources for freelancers, contractors, and entrepreneurs.

Professional

Guidance

Start with a few questions and explore from there.

Built for people who work differently

Traditional benefits don't always work for people outside traditional employment. IBN360 provides healthcare and other resources for:

  • Self-employed professionals who manage their own benefits.

  • 1099 workers and contractors who don't receive traditional employer benefits.

  • Freelancers and entrepreneurs who need resources that work outside a traditional workplace.

  • People between jobs who need another way to access healthcare.

  • Individuals and families looking for affordable healthcare options.

Built for people who work differently

Traditional benefits don't always work for people outside traditional employment.

IBN360 provides healthcare and other resources for:

  • Self-employed professionals who manage their own benefits.

  • 1099 workers and contractors who don't receive traditional employer benefits.

  • Freelancers and entrepreneurs who need resources that work outside a traditional workplace.

  • People between jobs who need another way to access healthcare.

  • Individuals and families looking for affordable healthcare options.

REAL-LIFE SITUATIONS

WHERE IBN360
FITS

Independent work comes with a lot to manage. Here are a few everyday situations and resources you can explore through IBN360.

01

Juggling Work, Bills & Healthcare

An independent professional may be managing clients, monthly expenses, and healthcare decisions at the same time.

Explore: Healthcare navigation and educational resources.
02

Managing an Income That Changes

Freelance and contract income can vary while bills and everyday financial responsibilities continue.

Explore: Budgeting, saving, debt, and financial wellness resources.
03

Thinking About What Comes Next

Planning for income, family responsibilities, and the future can be another thing to manage alongside work.

Explore: Protection planning information and educational resources.
04

Running a Business & Managing Life

Business owners often balance customers, daily operations, personal finances, and other responsibilities.

Explore: Business and independent professional resources.

Example situations are for educational and illustrative purposes only. Resources, eligibility, costs, benefits, and availability may vary.

Workshops

Support that isn't tied to one employer

The way people work has changed. Benefits should work for people who are self-employed, freelance, contract, run a business, or move between jobs.

  • Explore: See what's available based on what you're looking for.

  • Learn: Understand your options in simple language.

  • Ask: Get additional guidance when you have questions.

  • Decide: Choose what makes sense for your situation.

No pressure. No complicated process.

Member Testimonials

"Health Insurance Success Story"

Finally an affordable health insurance policy for the whole family. Independent contractors and 1099 workers are no longer out in the cold when it comes to healthcare. Be rewarded for your healthy lifestyle and tenacity to go it alone and don’t worry about premiums that drain your bank account.

"Licensed IBN360

Specialist"

I’m in awe of how simple and fast the process is to get clients price quotes and breakdown of the advantages IBN360 offers so that they can compare to their current situations. Not one has been disappointed with what they’ve heard. After a quick 10-minute information gathering, clients are set up and good to go. You can feel their sighs of relief.

"Health Insurance Success Story"

With health insurance premiums continuing to rise, I am so grateful to have found this program. Now I finally have an affordable and customizable health insurance plan for me and my family. Thank you IBN360!

"Health Insurance

Quote"

The switch to this plan saved my wife $450/mth ($5,400/yr); which also included a deductible that was $6,000 lower. Her PCP was in-network. Our family is thrilled and grateful to have such a positive financial impact.

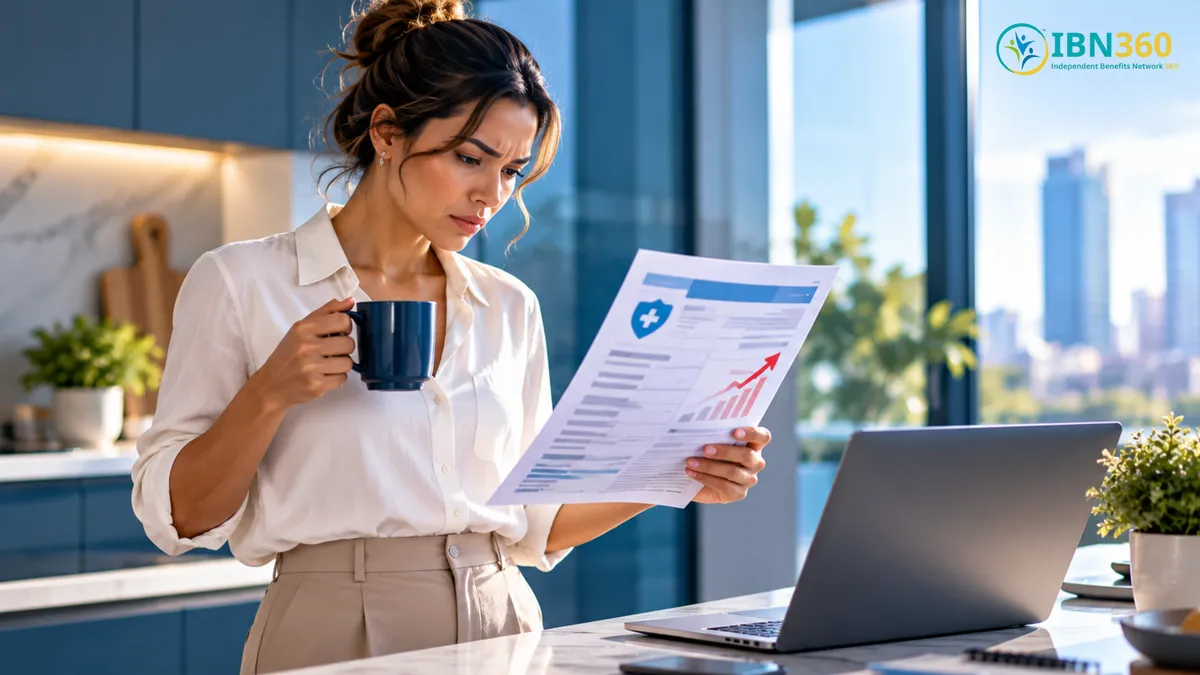
Woman reviewing Marketplace health insurance premium information beside a laptop in a home office

Why Marketplace Health Insurance Premiums Could Rise Again in 2027 | IBN360

September 30, 2026•4 min read

Suppose your 2027 renewal arrives and the monthly premium is higher. That can be hard to square with a year when you barely used the plan. Maybe you had a physical, filled a few prescriptions, and never came close to your deductible. Yet your renewal price can still change.

In its August 3, 2026 update, the Peterson-KFF Health System Tracker reported a median proposed Marketplace premium increase of 15% for 2027 across 276 insurers in all 50 states and the District of Columbia. The median finalized increase for 2026 was 20%. If those proposed increases broadly hold, 2027 would mark the second straight year of double-digit increases. (Source: Peterson-KFF Health System Tracker)


Your Doctor Visits Do Not Set Your Renewal Price

A renewal premium is not a tally of how often you personally went to the doctor. Marketplace insurers cannot use your health or medical history to raise your individual premium. Their overall rates still reflect what they expect it will cost to cover the broader pool in the coming year. (Source: HealthCare.gov)

That is why using very little care yourself does not freeze next year's price. If expected claims across the pool become more expensive, insurers account for that expected spending when setting rates.

The 15% headline also does not mean your monthly payment will automatically rise 15%. It describes proposed insurer rate changes before premium tax credits. Eligible households may still receive premium tax credits, even though the temporary enhanced credits expired after 2025. What you pay depends on the assistance you qualify for and the plan you select.


The Increase Starts Long Before the Renewal Notice

In detailed filings from 77 insurers across 16 states and D.C., KFF found a median projected medical and prescription cost increase of 10% for 2027, compared with about 8% in recent years. The forecast reflects higher prices and increased use of care.

Hospital services, physician care, labor costs, and prescription spending all feed into those projections. Insurers also cited the cost and growing use of GLP-1 drugs used for diabetes and weight management, along with other specialty medications. GLP-1 drugs are only one part of a broader cost forecast that also includes hospital care, physician services, labor, and other prescription spending.

Enrollment changes affect those projections too. Insurers expected healthier customers to be more likely to leave Marketplace coverage after enhanced financial assistance expired, leaving a remaining group expected to cost more to cover on average.


Who Stays Insured Changes the Math

KFF found that Marketplace enrollment among people who paid their premiums fell from 21.8 million in February 2025 to 19.2 million in February 2026, a 12% decline. The drop coincided with the expiration of enhanced premium tax credits at the end of 2025. (Source: KFF)

Enrollment totals alone cannot tell us exactly who left or why. The insurer filings provide the other piece: companies were pricing for the expectation that healthier customers would be more likely to leave as financial assistance decreased.

When healthier people leave, the remaining group can cost more to insure even before medical prices rise. That is one reason a person with a quiet year of healthcare can still open a renewal notice and find a higher price.


A Cheaper Premium Can Move the Cost Somewhere Else

In 2026, the average Marketplace deductible rose 37%, from $2,759 to $3,786. KFF found that much of the increase reflected people shifting toward lower-premium, higher-deductible plans. It does not mean every plan increased its deductible by 37%. (Source: KFF)

Suppose one plan saves $50 a month. That is $600 over a year. A deductible that is $2,000 higher does not automatically mean spending $2,000 more. Compare what each plan would charge for the care you expect, including prescriptions, copays, coinsurance, and services covered before the deductible.

If you qualify for cost-sharing reductions, compare Silver plans before moving to a lower-premium category. Eligible Silver plans can lower your deductible, copays, coinsurance, and out-of-pocket maximum. Those extra savings generally require choosing a Silver plan. (Source: HealthCare.gov)

For people who use HealthCare.gov, Open Enrollment for 2027 coverage starts November 1, 2026. If your state runs its own Marketplace, check its enrollment schedule. Updating your expected household income and completing the application will show the prices and savings available to you.

IBN360's guide to being covered and still owing thousands explains how deductibles, networks, and prescriptions can affect what you pay after you use your coverage.

Where services are available, you can schedule a conversation through IBN360 with a licensed coverage specialist. IBN360 is a health coverage navigation platform, not a health insurance carrier. Coverage discussions, quotes, and enrollments are handled by licensed specialists. Coverage availability, rates, and benefits vary by state.

Before renewing, compare the annual premium with what each plan would charge for your prescriptions and expected visits. Then stress-test the plan against an expensive surprise, such as a hospital stay. The monthly premium is only one part of what coverage may cost you in a year when you need it.


See coverage more clearly with IBN360.

This article is for educational purposes and does not replace individualized insurance guidance. Coverage, pricing, benefits, eligibility, and available options vary by plan, location, and individual circumstances.
ACA Marketplace premiums 2027health insurance premium increaseMarketplace premium tax credits
Back to Blog

Member Testimonials

"Health Insurance Success Story"

Finally an affordable health insurance policy for the whole family. Independent contractors and 1099 workers are no longer out in the cold when it comes to healthcare. Be rewarded for your healthy lifestyle and tenacity to go it alone and don’t worry about premiums that drain your bank account.

"Licensed IBN360

Specialist"

I’m in awe of how simple and fast the process is to get clients price quotes and breakdown of the advantages IBN360 offers so that they can compare to their current situations. Not one has been disappointed with what they’ve heard. After a quick 10-minute information gathering, clients are set up and good to go. You can feel their sighs of relief.

"Health Insurance Success Story"

With health insurance premiums continuing to rise, I am so grateful to have found this program. Now I finally have an affordable and customizable health insurance plan for me and my family. Thank you IBN360!

"Health Insurance

Quote"

The switch to this plan saved my wife $450/mth ($5,400/yr); which also included a deductible that was $6,000 lower. Her PCP was in-network. Our family is thrilled and grateful to have such a positive financial impact.

Woman reviewing Marketplace health insurance premium information beside a laptop in a home office

Why Marketplace Health Insurance Premiums Could Rise Again in 2027 | IBN360

September 30, 2026•4 min read

Suppose your 2027 renewal arrives and the monthly premium is higher. That can be hard to square with a year when you barely used the plan. Maybe you had a physical, filled a few prescriptions, and never came close to your deductible. Yet your renewal price can still change.

In its August 3, 2026 update, the Peterson-KFF Health System Tracker reported a median proposed Marketplace premium increase of 15% for 2027 across 276 insurers in all 50 states and the District of Columbia. The median finalized increase for 2026 was 20%. If those proposed increases broadly hold, 2027 would mark the second straight year of double-digit increases. (Source: Peterson-KFF Health System Tracker)


Your Doctor Visits Do Not Set Your Renewal Price

A renewal premium is not a tally of how often you personally went to the doctor. Marketplace insurers cannot use your health or medical history to raise your individual premium. Their overall rates still reflect what they expect it will cost to cover the broader pool in the coming year. (Source: HealthCare.gov)

That is why using very little care yourself does not freeze next year's price. If expected claims across the pool become more expensive, insurers account for that expected spending when setting rates.

The 15% headline also does not mean your monthly payment will automatically rise 15%. It describes proposed insurer rate changes before premium tax credits. Eligible households may still receive premium tax credits, even though the temporary enhanced credits expired after 2025. What you pay depends on the assistance you qualify for and the plan you select.


The Increase Starts Long Before the Renewal Notice

In detailed filings from 77 insurers across 16 states and D.C., KFF found a median projected medical and prescription cost increase of 10% for 2027, compared with about 8% in recent years. The forecast reflects higher prices and increased use of care.

Hospital services, physician care, labor costs, and prescription spending all feed into those projections. Insurers also cited the cost and growing use of GLP-1 drugs used for diabetes and weight management, along with other specialty medications. GLP-1 drugs are only one part of a broader cost forecast that also includes hospital care, physician services, labor, and other prescription spending.

Enrollment changes affect those projections too. Insurers expected healthier customers to be more likely to leave Marketplace coverage after enhanced financial assistance expired, leaving a remaining group expected to cost more to cover on average.


Who Stays Insured Changes the Math

KFF found that Marketplace enrollment among people who paid their premiums fell from 21.8 million in February 2025 to 19.2 million in February 2026, a 12% decline. The drop coincided with the expiration of enhanced premium tax credits at the end of 2025. (Source: KFF)

Enrollment totals alone cannot tell us exactly who left or why. The insurer filings provide the other piece: companies were pricing for the expectation that healthier customers would be more likely to leave as financial assistance decreased.

When healthier people leave, the remaining group can cost more to insure even before medical prices rise. That is one reason a person with a quiet year of healthcare can still open a renewal notice and find a higher price.


A Cheaper Premium Can Move the Cost Somewhere Else

In 2026, the average Marketplace deductible rose 37%, from $2,759 to $3,786. KFF found that much of the increase reflected people shifting toward lower-premium, higher-deductible plans. It does not mean every plan increased its deductible by 37%. (Source: KFF)

Suppose one plan saves $50 a month. That is $600 over a year. A deductible that is $2,000 higher does not automatically mean spending $2,000 more. Compare what each plan would charge for the care you expect, including prescriptions, copays, coinsurance, and services covered before the deductible.

If you qualify for cost-sharing reductions, compare Silver plans before moving to a lower-premium category. Eligible Silver plans can lower your deductible, copays, coinsurance, and out-of-pocket maximum. Those extra savings generally require choosing a Silver plan. (Source: HealthCare.gov)

For people who use HealthCare.gov, Open Enrollment for 2027 coverage starts November 1, 2026. If your state runs its own Marketplace, check its enrollment schedule. Updating your expected household income and completing the application will show the prices and savings available to you.

IBN360's guide to being covered and still owing thousands explains how deductibles, networks, and prescriptions can affect what you pay after you use your coverage.

Where services are available, you can schedule a conversation through IBN360 with a licensed coverage specialist. IBN360 is a health coverage navigation platform, not a health insurance carrier. Coverage discussions, quotes, and enrollments are handled by licensed specialists. Coverage availability, rates, and benefits vary by state.

Before renewing, compare the annual premium with what each plan would charge for your prescriptions and expected visits. Then stress-test the plan against an expensive surprise, such as a hospital stay. The monthly premium is only one part of what coverage may cost you in a year when you need it.


See coverage more clearly with IBN360.

This article is for educational purposes and does not replace individualized insurance guidance. Coverage, pricing, benefits, eligibility, and available options vary by plan, location, and individual circumstances.
ACA Marketplace premiums 2027health insurance premium increaseMarketplace premium tax credits
Back to Blog

Workshops

YOUR GOALS. YOUR CHOICES.

Get the Healthcare You Need at a Price That Works for You

Meet with an IBN360 specialist to learn about our healthcare network, review affordable pricing options, and get a quote based on your needs.

Workshops

YOUR GOALS. YOUR CHOICES.

Get the Healthcare You Need at a Price That Works for You

Meet with an IBN360 specialist to learn about our healthcare network, review affordable pricing options, and get a quote based on your needs.

Copyright (c) 2026 IBN360. All rights reserved

Privacy Policy I Terms and Conditions

Certain Programs and Benefits May Vary by States

IBN360 is a health coverage navigation platform. IBN360 is not a insurance carrier. All coverage discussions, quotes, and enrollments are handled by licensed specialists. Coverage availability, rates, and benefits vary by state.